
Every so often, the optical communications industry goes through a collective wave of anxiety about “technology replacement.” The 2026 version is about CPO (co-packaged optics). After NVIDIA announced that it would deploy CPO technology at scale in 2026, voices saying “pluggable optical modules are about to be phased out” could be heard everywhere. But if you actually walk into a North American CSP's data center and talk with the engineers responsible for architecture selection, you will find that the story is far from that simple.
CPO's core value proposition is clear. By co-packaging the optical engine and the switch ASIC on the same substrate, CPO shortens the electrical signal path from centimeters to millimeters, significantly reducing power consumption and signal loss. IEEE research data shows that current CPO transceivers are 67% more energy-efficient than DSP solutions and have a 23% advantage over LPO solutions; when the switch ASIC host SerDes is included, the energy-efficiency gains reach 69% and 44%, respectively. These figures are convincing, especially for AI training clusters whose power density is already approaching thermal limits.
But between technical advantage and commercial deployment, there is often a gap formed by operational reality. In front-line research with North American CSPs, one concern comes up repeatedly: maintainability. The core advantage of pluggable optical modules is precisely that they are “pluggable”—if any port fails, operations staff can replace the module within minutes without interrupting other links. CPO, by contrast, solders the optical engine onto the switch motherboard. Once an optical channel fails, the scope of impact and the complexity of repair are on a completely different level.
More critical is the issue of ecosystem openness. North American CSPs generally prefer multi-vendor strategies and do not want to be locked into a single vendor’s system-level solution. After years of standardization and multi-source agreement (MSA) development, pluggable optical modules have formed a mature open ecosystem. Compatible modules can be obtained from multiple suppliers, cost trends are predictable, and manufacturing experience is deep. CPO is still largely a system-vendor-led solution, and CSPs must consider the long-term risks of vendor lock-in when choosing it.
From the perspective of actual deployment scenarios, the division of labor between CPO and pluggable optical modules is becoming clearer. In Scale-Out networks—that is, connections between servers and switches and between switches within a data center—pluggable optical modules remain the absolute mainstream. These scenarios require flexible configuration of ports at different speeds and transmission distances and need to support phased upgrade schedules. The operational flexibility of pluggable modules is irreplaceable. GF Communications’ North America research report estimates that CPO switch shipments in Scale-Out scenarios will be less than 100,000 units in 2027, and pluggable optical modules will still hold an absolutely dominant position for years to come.
In Scale-Up scenarios—that is, high-speed interconnection between GPUs—the situation is different. Here, the requirements for bandwidth density and power consumption are more extreme, and both CPO and NPO (near-packaged optics) have opportunities. Several CSPs favor NPO or pluggable optical modules as a transitional route in their self-developed ASIC racks, and the pace of NPO deployment is believed to be faster and more robust than that of CPO.
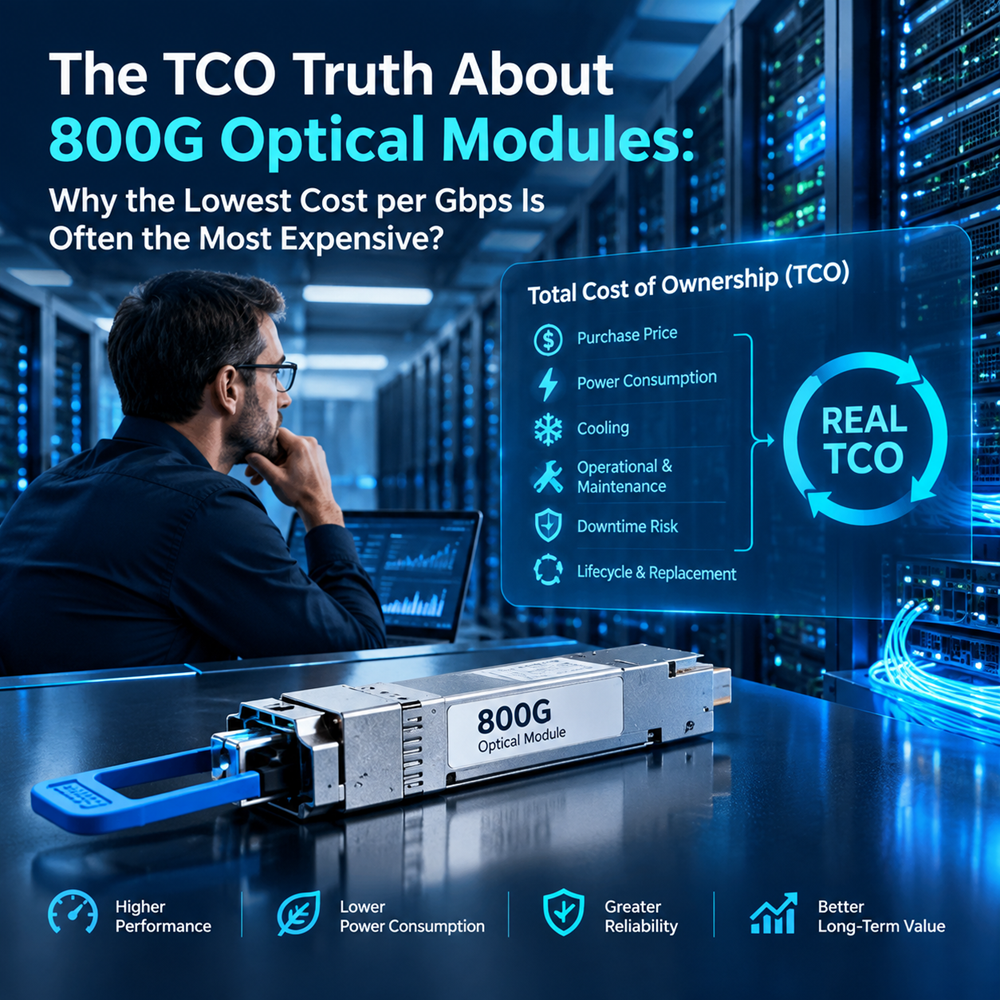
For optical module buyers, what does this technology roadmap debate actually mean? Simply put, you do not need to make an “either-or” decision between CPO and pluggable. Over the next five to ten years, the two technologies will coexist at different layers of AI data centers. Your procurement strategy should be based on specific deployment scenarios: for Scale-Out networks, continue to rely on pluggable optical modules as the main force, with close attention to suppliers’ capacity certainty and multi-platform compatibility for 800G and 1.6T products; for extreme scenarios such as GPU interconnection, you can begin evaluating the feasibility of NPO or CPO solutions, but there is no need to rush into large-scale switching.
What you really need to watch out for is not the change in the technology roadmap itself, but choosing a “transitional” supplier during the technology transition period. A supplier with mature mass-production capability and extensive platform compatibility experience in 800G pluggable modules will often have better technology continuity and supply chain stability when evolving to 1.6T and extending to NPO/CPO. In a period of rapid technology roadmap shifts, this continuity is itself a scarce competitive advantage.