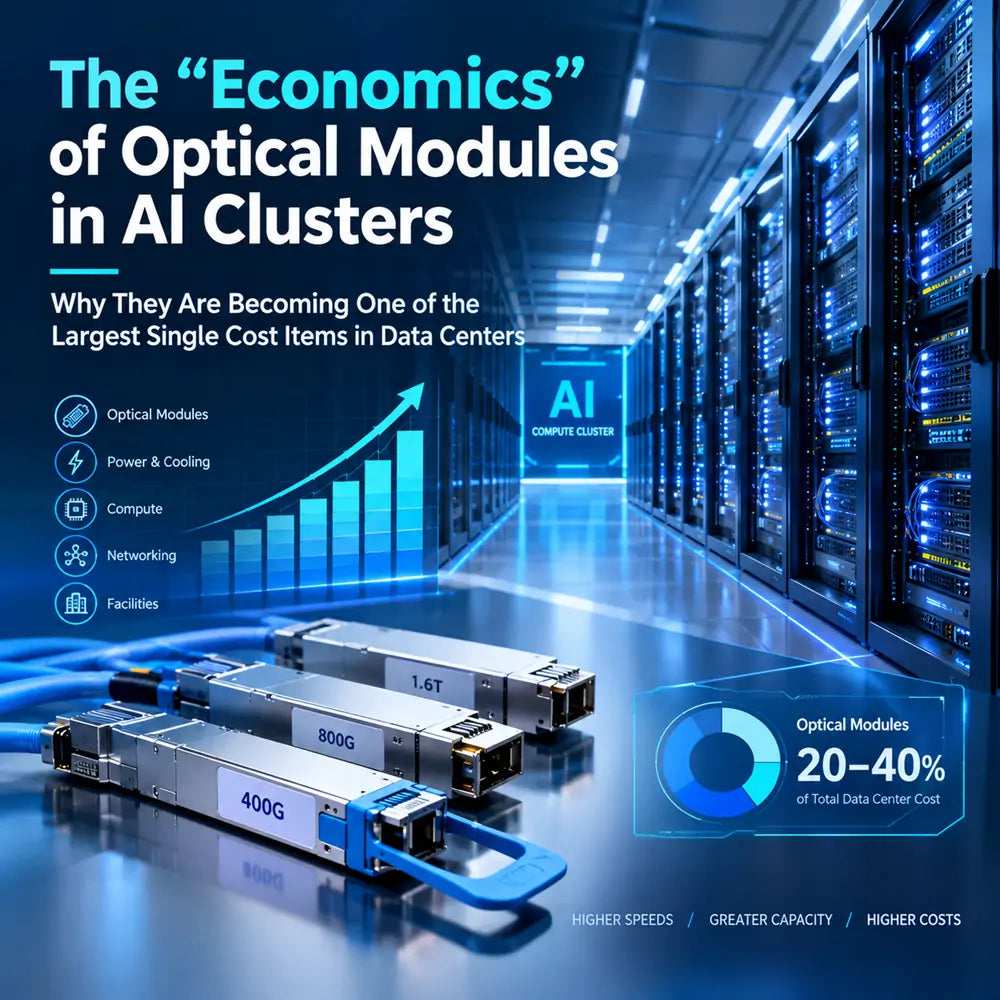

In 2026, the global optical transceiver market is undergoing an unprecedented structural transformation. According to the latest research from TrendForce, the global AI optical transceiver market is projected to grow from $16.5 billion in 2025 to $26 billion in 2026, representing year-over-year growth of more than 57%. Behind this rapid expansion is annual traffic growth of over 30% in North American hyperscale data centers, driving cloud computing giants such as Google, Microsoft, and Meta to continuously expand their deployments of GPUs and AI servers.
For international buyers, the commercialization of 1.6T optical transceivers is undoubtedly the most important development to watch in 2026. Major international technology companies have directly doubled their 2026 procurement plans for 1.6T optical transceivers, increasing them from 10 million to 20 million units. This surge in demand reflects the intensifying competition for AI computing power. A single GB200 server requires 162 1.6T optical transceivers to maintain data transmission efficiency. This firm demand is reshaping the entire supply chain.
Meanwhile, 800G optical transceivers continue to serve as the market's primary volume driver. Goldman Sachs has significantly revised its 2026 sales forecast for 800G optical transceivers upward, from 25 million to 33.5 million units, an increase of 58%. The combined demand from four major North American cloud providers—Meta, Google, Microsoft, and Amazon—is projected to exceed 37.5 million units, making them the world's largest group of buyers. This means that companies that establish stable supply relationships during this critical window will be better positioned to capitalize on the next wave of data center construction.
In terms of technology roadmaps, silicon photonics is rapidly gaining ground over traditional EML-based solutions. According to a research report by Galaxy Securities, silicon photonics is expected to account for more than 50% of 800G optical transceivers in 2026, with its share of the 1.6T market projected to reach 70%–80%. The core advantages of silicon photonics are lower power consumption and lower costs. Huawei's announcement of the world's first 1.6 Tbps single-wavelength silicon photonics module provides one example. By adopting third-generation silicon photonic integration technology, the module achieves a 70% reduction in size and a 40% reduction in power consumption. For buyers, choosing suppliers with in-house silicon photonics R&D capabilities not only offers a more favorable cost structure but can also mean shorter lead times and more reliable production capacity.
Supply chains are another defining issue in 2026. Lead times for 800G and higher-speed optical transceivers have generally exceeded 40 weeks, while some critical components are experiencing extreme lead times of 52 to 60 weeks. Supplies of key optoelectronic chips, including EML lasers and continuous-wave (CW) lasers, remain tight, making component availability the primary bottleneck to capacity expansion. Under these conditions, suppliers with sufficient component inventories and large-scale manufacturing capabilities are becoming increasingly scarce and valuable resources. Innolight has indicated that its existing orders already cover the entire year of 2026, with some orders extending into 2027.
For buyers and distributors evaluating suppliers, procurement strategies in 2026 need to shift from “comparing prices” to “comparing delivery capabilities.” Few manufacturers can deliver 800G and 1.6T products in large volumes. Meeting demand requires overcoming multiple challenges, including technical barriers, market access requirements, and manufacturing yields. As a result, actual delivery volumes received by customers may fall far short of expectations. Partnering with brands that have established silicon photonics expertise, a global manufacturing footprint, and mature supply chain management systems therefore offers greater strategic value than pursuing short-term low prices.
The procurement window spanning 2026 and 2027 will not remain open for long. Securing reliable, high-quality suppliers in advance will directly influence a company's competitive position over the following two to three years.